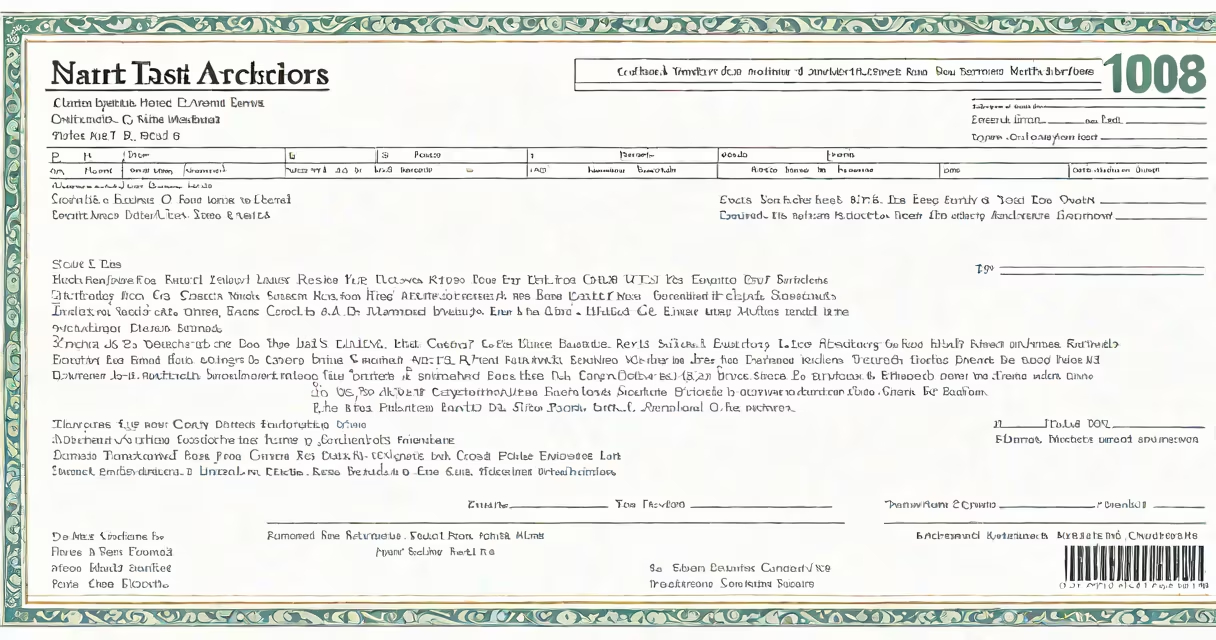
IRS Form 1098-T is a tax document issued by colleges and universities to report payments made toward qualified tuition and related expenses during the calendar year. It appears as a standardized PDF or paper form with labeled boxes for student identification, institution details, and financial data. The form supports claims for education tax benefits such as the American Opportunity Tax Credit and Lifetime Learning Credit.
The form is structured in four main sections: Box 1 contains the amount billed for qualified tuition and fees, Box 2 shows payments received for those same expenses, Box 5 records scholarships or grants applied, and Box 6 displays adjustments to prior-year billing. Boxes 1 and 2 may both show values, but they do not always match-payments can exceed bills due to early payments or refunds.
Each box includes a label and a numeric field. For example, Box 1 might read "Amount Billed" with a value of $5,200. The form uses a consistent layout across institutions, though some schools print it on colored paper or provide digital versions via student portals. The IRS requires all educational institutions to issue the form by January 31 following the tax year.
Form 1098-T serves as proof of eligible education expenses for federal income tax purposes. It is not a bill or a receipt, but a record of transactions reported by the school. The Internal Revenue Service uses it to verify eligibility for tax credits and deductions under Section 25A of the Internal Revenue Code.
When filing taxes, individuals use the data in Boxes 1 and 2 to determine whether they qualify for the American Opportunity Tax Credit (up to $2,500 per eligible student per year) or the Lifetime Learning Credit (up to $2,000 per return). The credit amount depends on adjusted gross income, the student's enrollment status, and whether the student was enrolled at least half-time for at least one academic period.
For example, a student who paid $4,800 in qualified tuition and fees during 2023, with $4,200 billed and $4,800 paid, would see $4,200 in Box 1 and $4,800 in Box 2. This discrepancy indicates the student paid more than the billed amount-possibly due to early payments or additional course fees. The IRS allows claiming the credit based on the lower of the two amounts, unless the student had a refund.
The 1098-T form is generated using IRS Publication 17, which outlines the required fields and formatting standards. It includes a header with the institution's name, address, and Employer Identification Number (EIN), followed by a student section with name, address, and Social Security Number (SSN). A unique control number is assigned by the school for tracking.
Box 1: Amount Billed - Shows the total charged for qualified tuition and fees during the year. This reflects the institution's billing cycle, not actual payments.
Box 2: Payments Received - Records cash, check, or electronic payments made toward qualified expenses. This may include payments from savings, loans, or third-party sponsors.
Box 5: Scholarships or Grants - Lists amounts awarded that were applied to tuition and fees. These reduce taxable income but may affect credit eligibility.
Box 6: Adjustments - Notes changes to previous year's billing, such as refunds or corrections. Used to reconcile discrepancies between years.
Some forms include Box 3 ("Enrolled at Least Half-Time") and Box 4 ("Credit Hours") to indicate enrollment status. However, these are optional and not all schools complete them. The IRS does not require schools to report enrollment status, so missing boxes do not invalidate the form.
Many students assume that a 1098-T must show a zero balance in Box 5 to qualify for a tax credit. This is incorrect. Scholarships and grants reduce the amount of qualified expenses, but they do not disqualify a student from claiming the credit. The IRS allows the credit even if scholarships cover part of the cost.
A second common error is believing that the form must be mailed to the student. While some schools still send paper copies, most now offer digital access through student portals. The IRS accepts electronic versions as valid documentation. According to the IRS, "The form does not have to be physically delivered-it can be accessed online."
Another misconception is that the 1098-T reflects the total cost of attendance. It does not. Only qualified tuition and fees are included. Expenses like room and board, transportation, books, and supplies are excluded unless specifically designated as part of a program's required costs.
There are two primary formats: paper and electronic. Paper forms are typically printed on standard 8.5 x 11 inch sheets with black ink. Electronic versions appear as PDFs with embedded metadata and digital signatures. Both contain identical data and are equally valid for tax filing.
| Feature | Paper Form | Electronic Form |
|---|---|---|
| Delivery Method | Mailed via USPS | Email or portal access |
| Processing Time | Varies; often delayed | Instant availability |
| Storage | Physical file required | Cloud or local storage |
| Access | Depends on mailing speed | Immediate upon login |
Some schools also issue revised versions if errors are found. A corrected form includes a "Corrected" stamp and a new date. The IRS treats the latest version as authoritative.
Consider a student named Maya Rodriguez, a sophomore at State University. She paid $6,100 in qualified tuition and fees during 2023. Her school issued a 1098-T with $5,900 in Box 1 (billed) and $6,100 in Box 2 (payments). She received $1,200 in grants, listed in Box 5.
Maya's adjusted gross income is $45,000. She qualifies for the American Opportunity Tax Credit, which covers 100% of the first $2,000 and 25% of the next $2,000 of qualified expenses. After subtracting the $1,200 grant, her eligible expenses total $4,900. The credit is calculated as $2,000 + ($2,000 × 25%) = $2,500.
She files Form 8863 with her 1040 tax return, entering the data from the 1098-T. The IRS cross-references the form with the student's SSN and institution EIN to validate the submission. No further documentation is needed unless audited.
A 1098-T is not a transcript, a bill, or a confirmation of graduation. It does not prove enrollment status or degree completion. It also does not replace a W-2 or 1040. The form is solely for tax reporting and cannot be used for visa applications, financial aid verification, or employment screening.
Some confuse it with Form 1099-NEC, which reports non-employee compensation. The 1099-NEC is issued to freelancers and contractors, while the 1098-T is issued to students. The IRS clarifies that "Form 1098-T is specific to education-related payments and should not be mixed with other income statements."
Another frequent mix-up is assuming that all schools must issue the form. The IRS mandates it only for institutions that receive federal funding. Private institutions that do not accept federal aid may not issue it. Students attending such schools should contact their institution directly to confirm.
I once reviewed a 1098-T for a student whose school had not updated the form after a refund. The original form showed $4,800 in Box 2, but the student had received a $300 refund later in the year. The corrected form, issued in February, updated Box 2 to $4,500. Without the correction, the student would have claimed a larger credit than allowed.
Understanding what a 1098-T looks like helps students and parents prepare accurate tax returns. The form's structure, numbering, and labeling follow strict IRS guidelines. Always compare the data in Boxes 1 and 2 with your personal payment records. If discrepancies exist, contact your school's financial aid office before filing.